

Ally Financial Inc.
NYSE: ALLY·Detroit, Michigan·CIK 0000040729
- Price
- $38.11
- Base IV
- $42.43
Valuation snapshot
At $38.11, the price sits between our bear case ($36.54) and base case ($42.43).
Values per share, from a Residual Income model.
- Book equity
- $42.17
- above today's price
- Base case
- $42.43
- above today's price · range $36.54–$51.28
- Price vs base case
- 10% below
- $38.11 against $42.43
- Book equity · balance sheet, quarter ended 2026-09-30no link today
- + Returns above required in base case · derived: base case − book equityderived, no source
- Base case · our researched forecast, 2026-11-05See the research ↗
- Price vs base · derived: price − base caseno reverse DCF for this method
- Price · StockValuer price feed, 2026-11-16 closeno link today
At $38.11 the price sits $4.06 below book equity of $42.17 a share: it pays for less than the capital already in the business.
Whisker on the base case runs bear $36.54 to bull $51.28. Values per share.
Price against each value
- Bear case
- $36.54
- Price 4% above
- No growth
- …
- —
- Base case
- $42.43
- Price 10% below
What does Ally Financial do?
Ally Financial provides automotive financing and insurance, corporate capital for private equity sponsors and middle-market companies, and banking services including deposits and investment advisory.
It brought in $1.2B of sales in the 12 months to Sep 2026.
Led by Michael G. Rhodes, Chief Executive Officer since 2024. Ally Leadership: Michael G. Rhodes
- Industry
- Financials
- Based in
- Detroit, Michigan
- Trades on
- NYSE as ALLY
Here is where each dollar a customer pays ends up. Out of every $1 of sales in the 12 months to Sep 2026, about $1.21 was left as profit after every cost, interest and tax. The biggest cost is tax, 33¢ of every dollar.
- Tax33¢
- Left as profit$1.21
Who pays Ally Financial, and for what?
Ally Financial is a digital bank and financial services company. It earns money from auto loans and leases, insurance, business lending, and banking services such as deposits and investing.
Its customers include consumers, auto dealers and retailers, businesses, municipalities, and private equity sponsors and asset managers.
Automotive Finance
71%Finances vehicle purchases and leases for consumers, dealers, businesses, and municipalities; also provides dealer inventory loans and vehicle remarketing services.
Insurance
22%Sells vehicle protection and insurance products to consumers through dealers, and commercial insurance products to dealers.
Corporate Finance
7%Provides secured loans, mainly to private equity-backed middle-market companies and asset managers.
Where its work physically happens, beyond headquarters:
- Ally Charlotte Center (corporate facility) — Charlotte, United States. Ally's 10-K names this owned facility of about 632,000 sq ft as one of its two principal corporate offices; it holds a large share of the executive, administrative and banking staff that run the Dealer Financial Services and Ally Bank deposit businesses.
- Ally Bank headquarters — Sandy, United States. Ally's own locations page lists this as the main office of Ally Bank, the Utah-chartered bank whose online deposits fund most of the company's auto loans and other lending.
- Lewisville operations center — Lewisville, United States. Ally bought this operations center, which it had been leasing, in June 2022; it supports servicing and customer operations for the large auto-finance loan book.
- Corporate Finance office — New York, United States. This leased office of about 55,000 sq ft (lease ends June 2033) is the main office of Ally's Corporate Finance segment, which lends to middle-market companies and adds commercial loan growth beyond auto.
How is the business doing?
Sales grew from $753M in 2020 to $1.2B in 2025, about 11% a year.
What does management say it's aiming for?
Ally says it aims to put people first and show up for customers' financial needs.
“We show up for our customers when it comes to their financial needs.”
Who is responsible for the plan?
- Michael G. RhodesChief Executive Officer
He leads Ally Financial and serves on its board of directors. Ally provides digital banking, automotive financing and insurance, and corporate finance services.
- Douglas TimmermanPresident, Dealer Financial Services
He oversees dealer relationships and Ally’s automotive finance and insurance services for dealers and consumers. Dealer Financial Services offers vehicle financing and insurance products to dealerships and their customers.
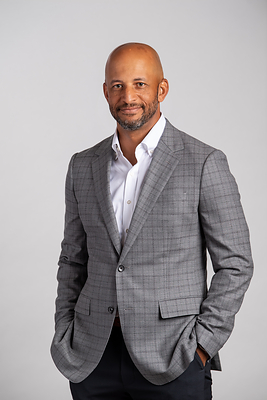 Mark MathewsonChief Information and Data Officer
He leads Ally’s technology and data organization across its functions and business lines. Ally uses technology and data to support its dealer and consumer products and services.
Roles checked November 6, 2026.
What management says it is working on now:
Grow auto finance carefully
Management aims to deepen dealer relationships, expand partnerships, and grow vehicle loan originations while keeping lending risk within its chosen limits.
Ally Financial 2025 Form 10-KExpand insurance
Management seeks to increase insurance sales through its dealer network and improve results through better processes and claims management.
Ally Financial 2025 Form 10-KGrow Corporate Finance selectively
Management plans to deepen existing relationships with private equity sponsors and asset managers, build new relationships, and consider lending opportunities in other markets.
Ally Financial 2025 Form 10-KBuild primary bank relationships
Ally Bank is focused on gaining customers who use it as their main bank and improving customer service and experiences.
Ally Financial 2025 Form 10-KUse technology to improve service and efficiency
Management plans to use data, AI, and automation to support customer-focused products and improve how the company operates.
Ally Financial 2025 Form 10-K
- Net interest margin, excluding certain accounting effects, 2026
- 3.6%–3.7%
- Ally Financial Q2 2026 Earnings Call Transcript
What's changing right now?
Growth is picking up. In Q3 2026 it sold 1% more than a year earlier. The year before, quarters averaged -3%.
Since Oct 2026 the share price has fallen 4%, from $39.64 to $38.11.
Coming up
October 20, 2026
Third-quarter 2026 results
Ally has scheduled its third-quarter results release and earnings call, where it is expected to report on business performance and discuss its outlook.
Earnings Releases & EventsThrough Q3 2027
GM Canada protection plan agreement
Ally's agreement to be GM Canada's preferred vehicle service contract and protection plan provider runs into the third quarter of 2027.
Ally Financial 2025 Form 10-K
What could go wrong?
No business is a sure thing. These are the risks we found, starting with the ones the company itself names. Where a risk would change part of the valuation, it says which.
Borrower defaults
A weaker economy, lower vehicle values, or lending decisions that do not work as expected could cause more borrowers or dealers to fall behind, increasing losses on auto and business loans.
From the company's own filingsWould hit how fast sales growAlly Financial 2025 Form 10-K
Dependence on dealers and auto sales
Ally relies on dealer relationships and U.S. vehicle sales. Changes in dealers' role, loss of important relationships, or a drop in vehicle sales could hurt its financing and insurance business.
From the company's own filingsWould hit how fast sales growAlly Financial 2025 Form 10-K
Funding and deposit pressure
Ally depends heavily on deposits to fund its lending. If customers move money elsewhere or Ally has to offer higher rates to retain deposits, funding may become more expensive or harder to obtain.
From the company's own filingsWould hit how much of each sale it keepsAlly Financial 2025 Form 10-K
Regulatory restrictions
New rules or supervisory actions could raise costs, limit products or growth, or restrict capital distributions. Requirements can also affect Ally's ability to expand its financial businesses.
From the company's own filingsWould hit how much of each sale it keepsAlly Financial 2025 Form 10-K
Technology and security failures
Ally depends on its own systems and outside service providers. A cyberattack, outage, or failed technology project could interrupt customer services, raise costs, or damage trust.
From the company's own filingsWould hit how much of each sale it keepsAlly Financial 2025 Form 10-K
Is it a good business?
From 2014 to 2017 it earned between -10% and 8% on its shareholders' equity, a median of 7%.
What might it be worth?
The Valuation snapshot at the top of this page shows the answer. This is how we got there. A share is a slice of the business, so what a share is worth depends on what the business can earn for its owners from here on. We estimate that three ways, from cautious to hopeful, and call the result .
For a bank, the cash it makes is hard to separate from the borrowing and deposits it runs on, so we start from the shareholders' capital already in it, its book equity, and add what it earns above the return those shareholders require. Today a share costs $38.11. Our put its value between $36.54 and $51.28, with $42.43 in the middle.
Bear case, $36.54
A prolonged period of high loan losses and expensive deposits depresses profitability, leaving little capital to grow the bank's worth.
Base case, $42.43
As loan defaults stabilize and lower interest rates reduce funding costs, the business steadily earns its required return and moderately builds value.
Bull case, $51.28
Strong lending margins, low loan defaults, and customer loyalty drive superior profitability, helping the company rapidly build its equity value.
Test the assumptions
Every valuation rests on a few judgments, and ours are only one set. This one turns on three: how much the bank earns on its equity, how long it keeps an edge over what shareholders require, and how fast its equity grows. The full research shows the evidence behind each.
- We assumed a return on equity of9.5%
- We assumed its edge over the required return lasts3 + 8 years
- We assumed book equity grows4.5% a year
This is an educational explanation built from public filings and our own research, not investment advice. It does not tell you whether to buy or sell anything.
Base estimate
$42.43 11.3%