
BRUNSWICK CORP
NYSE: BC·Mettawa, Illinois·CIK 0000014930
- Price
- $76.45
- Base IV
- $59.60
Valuation snapshot
At $76.45, the price sits between our base case ($59.60) and bull case ($117.97).
Values per share, from an .
- No growth
- …
- Loading earnings power
- Base case
- $59.60
- 78% of the price · range $18.92–$117.97
- Price vs base case
- 28% above
- $76.45 against $59.60
- Base case · our researched forecast, 2026-11-06See the research ↗
- Price vs base · derived: price − base caseWhat the price expects ↗
- Price · StockValuer price feed, 2026-11-16 closeno link today
The price has fallen 3.1% since this valuation was struck on 2026-11-06, so some of the gap opened up after these figures were set.
Whisker on the base case runs bear $18.92 to bull $117.97. Values per share.
Price against each value
- Bear case
- $18.92
- Price 304% above
- No growth
- …
- —
- Base case
- $59.60
- Price 28% above
What does Brunswick do?
Brunswick Corporation designs, manufactures, and distributes marine engines, propulsion systems, electronics, and parts for the recreational and commercial boating, RV, and industrial markets.
It brought in $5.7B of sales in the 12 months to Oct 2026.
Led by David M. Foulkes, Chief Executive Officer since 2019. Brunswick Corporation - Executive Leadership
- Industry
- Industrials
- Based in
- Mettawa, Illinois
- Trades on
- NYSE as BC
Here is where each dollar a customer pays ends up. Out of every $1 of sales in the 12 months to Oct 2026, about 4¢ was left as profit after every cost, interest and tax. The biggest cost is making what it sells, 74¢ of every dollar.
- Making what it sells74¢
- Research and development3¢
- Sales, marketing and admin16¢
- Everything else it takes to operate1¢
- Interest and other costs1¢
- Tax1¢
- Left as profit4¢
Who pays Brunswick, and for what?
Brunswick Corporation designs, manufactures, and markets marine recreation products. It makes money by selling outboard and inboard engines to boat builders and dealers, manufacturing boats under brands like Boston Whaler and Sea Ray, and supplying parts and electronics. It also generates recurring subscription fees from its Freedom Boat Club network.
Brunswick is paid by independent boat builders, marine dealers and distributors, aftermarket retailers, government agencies, and everyday consumers who purchase boats or boat club memberships.
Propulsion
Manufactures and sells outboard and inboard marine engines, controls, rigging, propellers, and electric motors under brands like Mercury Marine.
Mercury Verado outboard motor lower unit cutawayOutboardListings, CC BY-SA 4.0, via Wikimedia Commons Boat
Manufactures recreational boats across brands like Boston Whaler, Sea Ray, and Lund, and operates the Freedom Boat Club shared-access boat network.
Boston Whaler recreational boat on the waterEdward J. Clear at en.wikipedia, CC BY-SA 3.0, via Wikimedia Commons Engine Parts & Accessories
Distributes replacement parts, consumables, engine oils, lubricants, and marine electrical systems to dealers and service centers.
Navico Group
Designs and produces connected marine electronics, digital power systems, sonar, navigation displays, and sensors for marine and RV markets.
Where its work physically happens, beyond headquarters:
- Mercury Marine Fond du Lac — Fond du Lac, United States. This owned manufacturing and office campus is the principal listed site for the Propulsion and Engine P&A segments, so Mercury outboard engine output and capacity depend heavily on it.
- Boston Whaler Edgewater — Edgewater, United States. Boston Whaler's headquarters and manufacturing center absorbs production from the exited Flagler Beach plant, concentrating the brand's premium fiberglass boat output and the related consolidation savings at one site.
- Vonore Boat Plant — Vonore, United States. This listed Boat segment manufacturing site is part of the U.S. production base for a segment with $1,525.2 million of 2025 net sales.
- Brunswick Integrated Manufacturing Center — Merritt Island, United States. This Boat segment plant builds larger Sea Ray models such as the Sundancer 370 and SLX 400, which ties it to the premium end of the fiberglass boat range.
- Navico Group Ensenada — Ensenada, Mexico. This owned manufacturing and distribution site supports the Navico Group segment and gives the marine technology and electronics business a production base in Mexico, which also exposes it to cross-border trade costs.
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
How is the business doing?
Sales grew from $4.3B in 2020 to $5.4B in 2025, about 4% a year.
Running the business leaves about 6¢ of each sales dollar as operating profit, down from 12¢ in 2020.
After paying for its upkeep and new investment, it had $371.1M of cash to spare in the 12 months to Oct 2026.
What does management say it's aiming for?
Brunswick exists to be a global leader in marine recreation by delivering innovations that transform experiences on the water and beyond.
“delivering innovation that transforms experiences on the water and beyond.”
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
Who is responsible for the plan?
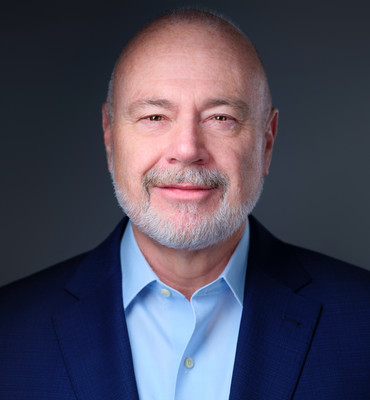 David M. FoulkesChief Executive Officer
Oversees the global enterprise, corporate strategy, operations, and execution across all business segments. Drives enterprise growth and financial performance across marine propulsion, boat manufacturing, and parts and accessories businesses.
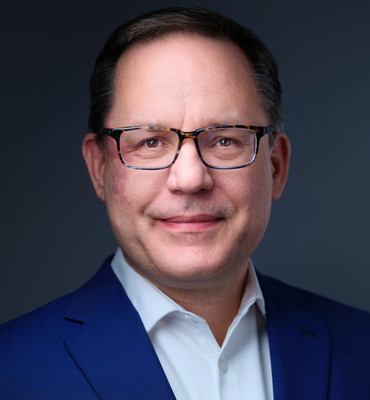 John G. BuelowExecutive Vice President and President, Mercury Marine
Leads global operations, manufacturing, and commercial strategies for the Mercury Marine propulsion division. Generates revenue through the manufacturing and sale of outboard, sterndrive, and inboard marine engines and related systems.
- Aine L. DenariExecutive Vice President, President of Navico Group, and Chief Technology Officer
Directs enterprise technology innovation, advanced digital solutions, and integrated electronics systems across the organization. Develops digital connectivity, marine electronics, and power management technologies embedded in products sold to consumers and OEM partners.
Roles checked November 6, 2026.
What management says it is working on now:
Advancing Marine Technology and ACES Initiatives
Investing in autonomy, connectivity, electrification, and shared access, including autonomous docking and radar systems to make boating easier and safer.
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025Expanding Shared Access and Boating Participation
Growing Freedom Boat Club locations globally and enhancing digital financing solutions to engage new and diverse boaters without traditional ownership hurdles.
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025Optimizing the Manufacturing Footprint
Consolidating production facilities into high-performing manufacturing hubs to lower fixed overhead costs and improve operational efficiency.
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025Disciplined Capital Strategy and Debt Reduction
Retiring debt and managing maturities while funding capital expenditures for new products, regular dividends, and share buybacks.
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025Enhancing Supply Chain Resiliency
Mitigating commodity price swings and tariff exposure through multi-sourcing strategies, pricing adjustments, and fixed-price contracts.
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
- Adjusted diluted EPS, full-year 2026
- approximately $4.65
- Brunswick Corporation Third Quarter 2026 Earnings Release
- Net sales, full-year 2026
- $5.7 billion to $5.8 billion
- Brunswick Corporation Third Quarter 2026 Earnings Release
- Adjusted operating margin, full-year 2026
- approximately 8.0%
- Brunswick Corporation Third Quarter 2026 Earnings Release
- Free cash flow, full-year 2026
- $400 million or more
- Brunswick Corporation Third Quarter 2026 Earnings Release
- Debt reduction, full-year 2026
- meet or exceed $160 million
- Brunswick Corporation Third Quarter 2026 Earnings Release
- Share repurchases, full-year 2026
- more than $80 million
- Brunswick Corporation Third Quarter 2026 Earnings Release
What's changing right now?
Growth is slowing. In Q3 2026 it sold 7% more than a year earlier. The year before, quarters averaged 11%.
Its operating margin is wider than a year ago: 7¢ per sales dollar, against a loss of 18¢.
Since Nov 2026 the share price has fallen 3%, from $78.96 to $76.45.
Recently
December 31, 2025
Annual Propulsion Segment Net Sales changed to $2.2B
Brunswick Corp Form 10-K FY 2025 Segment ReportingDecember 31, 2025
Annual Free Cash Flow changed to $396.3M
Brunswick Corp Form 10-K FY 2025 Non-GAAP Free Cash Flow Reconciliation
Coming up
January 1, 2027
Chief Executive Officer Succession
Current CEO David Foulkes transitions the leadership role to Áine Denari, the current Executive VP and President of Navico Group, steering corporate direction.
Brunswick Corporation Third Quarter 2026 Earnings ReleaseJanuary–February 2027
Winter and Spring Boat Show Season
Major international boat exhibitions, including Boot Düsseldorf and the Miami International Boat Show, set early consumer retail tone and determine wholesale inventory restocking.
Brunswick Corporation Third Quarter 2026 Earnings ReleaseBy December 31, 2026
Completion of Full-Year 2026 Debt Reduction Target
Retiring at least $160 million in total debt through the fiscal year lowers debt leverage and net interest expenses going into 2027.
Brunswick Corporation Third Quarter 2026 Earnings ReleaseThroughout 2026–2027
Commercial Rollout of Autonomous Marine Tech
Commercial deployment and boat-builder adoption of Simrad AutoCaptain autonomous docking and AutoTrack radar systems across production boat lines.
Brunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
Our own estimate moved too: the base case went from $66.18 to $59.60 a share between our last two valuations. The biggest reason: Annual Propulsion Segment Net Sales moved from an unreported prior value to $2.2B, as reported in Brunswick Corp Form 10-K FY 2025 Segment Reporting.
What could go wrong?
No business is a sure thing. These are the risks we found, starting with the ones the company itself names. Where a risk would change part of the valuation, it says which.
Consumer Sensitivity to Economic Conditions
Boats and marine engines are discretionary purchases that consumers readily postpone or cancel during economic downturns, high inflation, or weakening confidence.
From the company's own filingsWould hit how fast sales growBrunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
Tariffs and Global Trade Restrictions
Import tariffs on metals and components, along with retaliatory foreign duties on U.S. exports, inflate manufacturing costs and weaken product price competitiveness abroad.
From the company's own filingsWould hit how much of each sale it keepsBrunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
High Interest Rates and Dealer Financing Constraints
Elevated borrowing rates increase monthly retail boat payments and make dealer floor plan financing expensive, leading dealers to trim their wholesale orders.
From the company's own filingsWould hit how fast sales growBrunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
Reliance on Single-Source Suppliers
Several critical boat and engine components rely on limited or sole suppliers, making operations vulnerable to factory interruptions, parts shortages, or price increases.
From the company's own filingsWould hit how much of each sale it keepsBrunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
Manufacturing Facility Relocations and Consolidations
Closing plants and shifting production lines to different factories introduces risks of temporary manufacturing inefficiencies, delays, and unexpected transitional costs.
From the company's own filingsWould hit how much of each sale it keepsBrunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
IT Outages and Cybersecurity Incidents
Security breaches, ransomware, or software outages across core operational networks can halt factory lines, delay commercial shipments, and result in substantial financial penalties.
From the company's own filingsWould hit how fast sales growBrunswick Corp Form 10-K for the Fiscal Year Ended December 31, 2025
Consolidated net sales fell 18.2% in 2024 to 5.237 billion dollars and grew only 2.4% in 2025, demonstrating past vulnerability to dealer order cuts.
From our researchWould hit how fast sales growBrunswick Corp Form 10-K FY 2025
GAAP operating margins were compressed to 3.6% in Q1 2026 and negative 4.8% in Q4 2024 during the height of production cutbacks.
From our researchWould hit how much of each sale it keepsBrunswick Form 10-Q Q1 2026
Is it a good business?
From 2016 to 2025 it earned between -1% and 21% on the capital invested in it, a median of 18%. Its cost of capital in the latest valuation is 8.5%; returns were above it in 8 of the 10 years.
From 2016 to 2025 it earned between -10% and 33% on its shareholders' equity, a median of 18%.
Over 10 years its operating margin ranged from 1¢ to 14¢ per sales dollar, a median of 11¢. Gross margin ran from 25¢ to 29¢.
Cost of capital 8.5%
The number of shares has held roughly steady over the past year.
It owes $1.7B more than it holds in cash, about 5.4 years of operating profit.
What might it be worth?
The Valuation snapshot at the top of this page shows the answer. This is how we got there. A share is a slice of the business, so what a share is worth depends on what the business can earn for its owners from here on. We estimate that three ways, from cautious to hopeful, and call the result .
Today a share costs $76.45. Our put its value between $18.92 and $117.97, with $59.60 in the middle. Underneath sit two simpler checks: what it would cost to rebuild the business, its , and what today's profit is worth with no growth at all, its .
Bear case, $18.92
In this cautious scenario, elevated loan rates and hesitant consumers keep new boat demand subdued, leaving the company dependent on replacement parts and producing slow sales growth with constrained profitability.
Base case, $59.60
In this standard outlook, retail boat demand gradually stabilizes as dealer inventories balance out, enabling steady mid-single-digit sales gains and healthy operational profitability.
Bull case, $117.97
In this optimistic scenario, lower loan rates and renewed consumer enthusiasm revive boat sales, while premium engine market gains and boat club growth fuel brisk sales expansion and superior profit margins.
Another way in: instead of asking what the business is worth, ask what today's price assumes it will do.
Why the gap?
The price expects more than we do.Price above value: 28%
For Brunswick to be worth today's $76.45, sales would need to grow about 7.9% a year. We assume 3.7%. Over the last 5 years, sales grew 0.5% a year.
Or, if sales grow 3.7% as we assume, the price works with a profit margin of 11.4% (we assume 9.5%).
Keep in mind: this is one way to read the price. Investors might be expecting other things, like higher profits or lower risk.
Do you think sales can grow 7.9% a year?
Try your own numbersWe're moderately sure of this range: it scores 54 out of 100 on our checks. The weakest point is terminal-value dependency.
Test the assumptions
Our base value of $59.60 rests on three assumptions. Change any of them to see how the value per share responds.
- Revenue growth, 5-year average3.7%
- Operating margin9.5%
- Long-term growth rate2.3%
This is an educational explanation built from public filings and our own research, not investment advice. It does not tell you whether to buy or sell anything.
Base estimate
$59.60 -22.0%